Back in September I had forecasted AMD would be heading for a GAAP loss in Q1 or Q2 2007:
http://sharikou180.blogspot.com/2006/09/ati-revises-quarterly-guidance-down.html
Having seen Bob Rivet's presentation at their recent Analysts Day, I think it's time to reiterate that prediction for the following reasons:
1. While AMD eked out a 56 million $ profit in Q306, ATI lost almost the same amount. And...it does not look like ATI is going to win back market share from Nvidia in a hurry.
2. Their Q306 adjusted debt to capital ratio is at 37%. Of their plans to bring this down, I think "Improvements in working capital" & "Using excess cash flow" are questionable as they seem to make the assumption that they will continue to enjoy the same kind of profits they did in 2006. We shall have to wait and see on this one.
3. There is a 380 million $ acquisition related (intangibles/synergy related costs) write down which Rivet says will be front end loaded in 2007.
All this is going to impact their bottomline. I repeat - AMD is heading for a GAAP loss in either Q1 or Q2 2007. Intel on the other hand seems to have dodged the bullet the good Doctor Sharikou has been asserting and it looks like yet again one of his predictions is going to fall flat...since it is highly unlikely Intel will have a GAAP loss in Q406. Which incidentally was the fall back position when they did not have a GAAP loss in Q206 as he had originally predicted.
Wednesday, December 20, 2006


Google and Apple are on a collision course
Some time ago I wrote about how Apple was determined to become the Walmart of digital content:
http://sharikou180.blogspot.com/2006/09/apple-effect.html
After Google's 1.4 billion $ purchase of Youtube, I now believe Apple's biggest threat long term will be Google. Why...? It's because Google wants to ensure they own every online touch point possible to sell advertising. But not just any advertising. Google's promise is to sell effective advertising because it's targetted. In order to do this, over the long term Google will need to go significantly beyond regular search and own the digital entertainment content touch points. And not just "user generated content" or the boring television from the 70's they started out with on Google video. They will need to own what's hot and what's new. And this is what Apple wants to own too. The difference is Apple wants to sell you the content and Google wants to sell advertising on the content.
So either these guys are heading for a show-down, or they are heading to a partnership which shakes us all down by either selling us content or giving us content but selling advertising on that content. Perhaps now Otellini's presence on the Google board and his willingness to bend over backward for Steve are making a little sense. I thought it was only due to the fact that the 60,000 google shares he got are worth significantly more than his Intel holdings but perhaps I was wrong.
http://sharikou180.blogspot.com/2006/09/apple-effect.html
After Google's 1.4 billion $ purchase of Youtube, I now believe Apple's biggest threat long term will be Google. Why...? It's because Google wants to ensure they own every online touch point possible to sell advertising. But not just any advertising. Google's promise is to sell effective advertising because it's targetted. In order to do this, over the long term Google will need to go significantly beyond regular search and own the digital entertainment content touch points. And not just "user generated content" or the boring television from the 70's they started out with on Google video. They will need to own what's hot and what's new. And this is what Apple wants to own too. The difference is Apple wants to sell you the content and Google wants to sell advertising on the content.
So either these guys are heading for a show-down, or they are heading to a partnership which shakes us all down by either selling us content or giving us content but selling advertising on that content. Perhaps now Otellini's presence on the Google board and his willingness to bend over backward for Steve are making a little sense. I thought it was only due to the fact that the 60,000 google shares he got are worth significantly more than his Intel holdings but perhaps I was wrong.
Thursday, December 14, 2006
4x4 - it's a Hummer...not a Merc
I was reading this letter on The Inquirer (before you jump for your guns - I'm going to slay their opinion shortly) about how the 4x4 is the PC equivalent of a 400 horse powered Merc and not a Toyota and I had a violent convulsion of disagreement resulting in this post:
http://www.theinquirer.net/default.aspx?article=36319
(Pls read the article before reading the rest of the post)
Unfortunately, the dynamics and business models of the car business and the microprocessor business are two different things...at least this point in time (I'll talk more about how they could be converging in a later post).
1. The car industry is hyper-segmented with multiple models serving niche markets. A couple of hundred thousand units make a product/brand a viable proposition due to how their design and manufacturing allows them to optimise across. Further more, cosumer decision making works across multiple axis from speed, mileage to all the bells & whistles inside the car which allow easy brand/product differentiation.
The microprocessor business however has two primary vectors of comparision. Performance and now power consumption as a recent phenomena. Hence, everyone is expecting more performance with all the benefits of reduced power consumption (lower electricity bills, less heat, smaller form factors, etc).
2. In 2005 the Mercedes car group sold ~1 million units. Of which their top of the line models contributed only 72k units. In the microprocessor business the same does not hold true. At least for now. If AMD were to operate at the same scale as Mercedes and sell only 72k of it's top of the line product then it would be meeting with it's debtors pretty soon.
Now, I know I'm pushing it a bit using these two as a comparision but it's to make a point. The business models and scale of both these industries is vastly different. Can you imagine someone walking into Hector's office and telling him they will sell only 72k units of their top of the line platform.
3. The Merc is what it is because it is not only powerful, but also a thing of beauty. Unfortunately, the 4x4 is a loud, ugly beast. Which is why I think it's more a Hummer if we have to draw a parallel. Allows you to drive everywhere - on and off road but is expensive, pig ugly and guzzles gas faster than an 8 year old can eat candy.
The only bright spot for AMD if they follow GM's model is at least the sales of Hummer's seem to be increasing YoY. They've sold 65k of them so far in 2006.
http://www.theinquirer.net/default.aspx?article=36319
(Pls read the article before reading the rest of the post)
Unfortunately, the dynamics and business models of the car business and the microprocessor business are two different things...at least this point in time (I'll talk more about how they could be converging in a later post).
1. The car industry is hyper-segmented with multiple models serving niche markets. A couple of hundred thousand units make a product/brand a viable proposition due to how their design and manufacturing allows them to optimise across. Further more, cosumer decision making works across multiple axis from speed, mileage to all the bells & whistles inside the car which allow easy brand/product differentiation.
The microprocessor business however has two primary vectors of comparision. Performance and now power consumption as a recent phenomena. Hence, everyone is expecting more performance with all the benefits of reduced power consumption (lower electricity bills, less heat, smaller form factors, etc).
2. In 2005 the Mercedes car group sold ~1 million units. Of which their top of the line models contributed only 72k units. In the microprocessor business the same does not hold true. At least for now. If AMD were to operate at the same scale as Mercedes and sell only 72k of it's top of the line product then it would be meeting with it's debtors pretty soon.
Now, I know I'm pushing it a bit using these two as a comparision but it's to make a point. The business models and scale of both these industries is vastly different. Can you imagine someone walking into Hector's office and telling him they will sell only 72k units of their top of the line platform.
3. The Merc is what it is because it is not only powerful, but also a thing of beauty. Unfortunately, the 4x4 is a loud, ugly beast. Which is why I think it's more a Hummer if we have to draw a parallel. Allows you to drive everywhere - on and off road but is expensive, pig ugly and guzzles gas faster than an 8 year old can eat candy.
The only bright spot for AMD if they follow GM's model is at least the sales of Hummer's seem to be increasing YoY. They've sold 65k of them so far in 2006.
Monday, December 04, 2006
Quad FX - or is it Quad just for effect
Reviews and pricing for 4x4 are out comparing it to Kentsfield. Here are some of them:
http://www.firingsquad.com/hardware/amd_athlon_64_fx_74_4x4/default.asp
http://enthusiast.hardocp.com/article.html?art=MTIzMyw1LCxoZW50aHVzaWFzdA==
http://www.tomshardware.com/2006/11/30/brute_force_quad_cores/page13.html
http://www.hothardware.com/viewarticle.aspx?articleid=911&cid=1
I'm not the right guy to dissect the technical details but there are two things I was expecting:
1. This will be a power hungry, large and loud beast of a system. Which is correct.
2. That this would be a hard kick in the performance cojones for Kentsfield. Which to my astonishment is not correct.
From a pricing standpoint...this thing is priced extremely agressively (in pairs):
2 x FX70 = $599
2 x FX72 = $799
2 x FX74 = $999
Considering the FX62 is at 713$, this is quite a steep price drop. However, the issues with the system price overall is the cost of the mobo and the fact that there is only one supplier - Asus. My hypothesis is that AMD knows at this point Quad FX is only a marketing ploy. It is not a market winning solution until they bring out Barcelona. Hence, they do not want to enable all their partners at this stage until they have a better sense of whether they want to market Barcelona by itself or as part of Quad FX.
Having seen that the performance is not spanking Kentsfield, I think Intel will now accelerate their quad core ramp. They will bring pricing further down in Q107. Their intent will be the same as it was on dual core. To make quad core mainstream faster than expected and hence place supply and capacity pressure on AMD. Their hope will be AMD cannot ramp Barcelona fast enough and Quad FX is hardly a mainstream desktop solution. Hence, customers (starting with channel I guess) will once again feel AMD is unable to meet their needs.
So do expect Kentsfield to drop below 999$ in Q1. I'd assume this will be accompanied with a new SKU with a higher clock speed just to land a 1-2 punch on AMD.
----------------------------------------------------------------------------
UPDATE
Anandtech in his review shows a Quad COre at 2.4GHz in Q1 priced at $851. So Intel will bring Quad Core mainstreamish fast.
http://anandtech.com/cpuchipsets/showdoc.aspx?i=2879&p=3
Intel Core 2 Extreme QX6700 2.66GHz 4MB per 2 cores $999
Intel Core 2 Quad Q6600** 2.40GHz 4MB per 2 cores $851
Intel Core 2 Extreme X6800 2.93GHz 4MB $999
I suspect the scenarios AMD is playing with right now are:
1. If Barcelona kicks Conroe's performance and perhaps more importantly performance/watt ass then 4x4 will die an unnoticed death.
2. However, if Barcelona does not completely wipe the floor with Conroe. Even if it's better but only marginally better then AMD will increase the focus on 4x4 and try and bring platform price and thermals down. They may even introduce dual core flavours of Barcelona (not sure if this is already on their public plans) to drop into 4x4 just as Intel is potentially introducing single core versions of Conroe for the lower end of the market.
Of course, everyone (including me) are assuming Barcelona will wipe Conroe off the map. But I was also expecting 4x4 to do the same to Kentsfield and that is not the case so let's assume nothing till we see it for ourselves.
http://www.firingsquad.com/hardware/amd_athlon_64_fx_74_4x4/default.asp
http://enthusiast.hardocp.com/article.html?art=MTIzMyw1LCxoZW50aHVzaWFzdA==
http://www.tomshardware.com/2006/11/30/brute_force_quad_cores/page13.html
http://www.hothardware.com/viewarticle.aspx?articleid=911&cid=1
I'm not the right guy to dissect the technical details but there are two things I was expecting:
1. This will be a power hungry, large and loud beast of a system. Which is correct.
2. That this would be a hard kick in the performance cojones for Kentsfield. Which to my astonishment is not correct.
From a pricing standpoint...this thing is priced extremely agressively (in pairs):
2 x FX70 = $599
2 x FX72 = $799
2 x FX74 = $999
Considering the FX62 is at 713$, this is quite a steep price drop. However, the issues with the system price overall is the cost of the mobo and the fact that there is only one supplier - Asus. My hypothesis is that AMD knows at this point Quad FX is only a marketing ploy. It is not a market winning solution until they bring out Barcelona. Hence, they do not want to enable all their partners at this stage until they have a better sense of whether they want to market Barcelona by itself or as part of Quad FX.
Having seen that the performance is not spanking Kentsfield, I think Intel will now accelerate their quad core ramp. They will bring pricing further down in Q107. Their intent will be the same as it was on dual core. To make quad core mainstream faster than expected and hence place supply and capacity pressure on AMD. Their hope will be AMD cannot ramp Barcelona fast enough and Quad FX is hardly a mainstream desktop solution. Hence, customers (starting with channel I guess) will once again feel AMD is unable to meet their needs.
So do expect Kentsfield to drop below 999$ in Q1. I'd assume this will be accompanied with a new SKU with a higher clock speed just to land a 1-2 punch on AMD.
----------------------------------------------------------------------------
UPDATE
Anandtech in his review shows a Quad COre at 2.4GHz in Q1 priced at $851. So Intel will bring Quad Core mainstreamish fast.
http://anandtech.com/cpuchipsets/showdoc.aspx?i=2879&p=3
Intel Core 2 Extreme QX6700 2.66GHz 4MB per 2 cores $999
Intel Core 2 Quad Q6600** 2.40GHz 4MB per 2 cores $851
Intel Core 2 Extreme X6800 2.93GHz 4MB $999
I suspect the scenarios AMD is playing with right now are:
1. If Barcelona kicks Conroe's performance and perhaps more importantly performance/watt ass then 4x4 will die an unnoticed death.
2. However, if Barcelona does not completely wipe the floor with Conroe. Even if it's better but only marginally better then AMD will increase the focus on 4x4 and try and bring platform price and thermals down. They may even introduce dual core flavours of Barcelona (not sure if this is already on their public plans) to drop into 4x4 just as Intel is potentially introducing single core versions of Conroe for the lower end of the market.
Of course, everyone (including me) are assuming Barcelona will wipe Conroe off the map. But I was also expecting 4x4 to do the same to Kentsfield and that is not the case so let's assume nothing till we see it for ourselves.
Monday, November 27, 2006
A quick note on Dell's Q3
I've been away and pretty busy but I wanted to do a quick note on Dell's Q3. This was obviously a strong rebound for Dell in terms of revenue and more importantly profits even though HP grew share faster than them. I think primarily this quarter their move to Opteron in servers has definitely helped them. I also think their focus on trying to move their higher margin products has helped somewhat. But long term I continue to remain concerned by their lack of new strategic direction.
Their growth in China also I think will come under threat over the next 3-4 quarters as Lenovo trains their sights on Dell. And HP will not be happy knowing that Dell is managing to grow in spite of the fact that they have wrenched the #1 spot from them. All in all, I think Dell will probably have a good Q4. But by Q1 Lenovo and HP will start to attack them in desktops & servers respectively. Which means unless HP gets their act together Dell does have a relative opportunity in the notebook business. I am doubtful their Q3 results were really helped by their move to Turion since that was much later in the quarter. I suspect what happened their is they had their sales people focus on selling up in what is a very rapidly growing category.
Thoughts everybody...?
Their growth in China also I think will come under threat over the next 3-4 quarters as Lenovo trains their sights on Dell. And HP will not be happy knowing that Dell is managing to grow in spite of the fact that they have wrenched the #1 spot from them. All in all, I think Dell will probably have a good Q4. But by Q1 Lenovo and HP will start to attack them in desktops & servers respectively. Which means unless HP gets their act together Dell does have a relative opportunity in the notebook business. I am doubtful their Q3 results were really helped by their move to Turion since that was much later in the quarter. I suspect what happened their is they had their sales people focus on selling up in what is a very rapidly growing category.
Thoughts everybody...?
Friday, November 17, 2006
Intel increases dividends starting Q107
Intel increases dividends
After announcing a Q406 dividend, which I discussed here:
http://sharikou180.blogspot.com/2006/09/intel-announces-dividend.html
To further raise the dividend is not the sign of a company worrying about their cash position. What's going on here? Something has happened to give the board confidence that they can not only afford a dividend, they can increase it.
After announcing a Q406 dividend, which I discussed here:
http://sharikou180.blogspot.com/2006/09/intel-announces-dividend.html
To further raise the dividend is not the sign of a company worrying about their cash position. What's going on here? Something has happened to give the board confidence that they can not only afford a dividend, they can increase it.
Wednesday, November 15, 2006
Nvidia making out with Intel - I called it in September
I had said back in September that Nvidia and HP would get more aligned with Intel post the ATI acquisition. The Nvidia piece of that has started to materialize.
http://www.nvidia.com/object/IO_37234.html
I'm thinking this is only the first step and there will be more to come between Nvidia and Intel. To read the original post, go here:
New Bed-fellows
So far this week that's 2 predictions come right - this and the demise of the PIC.
http://www.nvidia.com/object/IO_37234.html
I'm thinking this is only the first step and there will be more to come between Nvidia and Intel. To read the original post, go here:
New Bed-fellows
So far this week that's 2 predictions come right - this and the demise of the PIC.
Monday, November 13, 2006
PIC is dead - I called it in September
In their quarterly filing AMD cancelled PIC. Scroll down to page 32:
AMD Q3 filing
I called this back in September when I said the cash being spent behind the ATI deal would force Hector to review which projects he continues to fund and perhaps the PIC would disappear.
New Bed-fellows
(Scroll down the post)
The point is not PIC itself which has very little material impact on AMD"s revenues. The point really is that AMD will have to now start to manage cash and debt very carefully and they will not be able to invest in as many areas as they have been. The second message in here as that Hector's 50x15 vision becomes only rhetoric. Which is unfortunate for the people who could have benefitted from it...but that's life. In this case, they definitely lived up to their slogan of "Smarter Choice". Just it was the smarter choice for themselves this time round -:)
AMD Q3 filing
I called this back in September when I said the cash being spent behind the ATI deal would force Hector to review which projects he continues to fund and perhaps the PIC would disappear.
New Bed-fellows
(Scroll down the post)
The point is not PIC itself which has very little material impact on AMD"s revenues. The point really is that AMD will have to now start to manage cash and debt very carefully and they will not be able to invest in as many areas as they have been. The second message in here as that Hector's 50x15 vision becomes only rhetoric. Which is unfortunate for the people who could have benefitted from it...but that's life. In this case, they definitely lived up to their slogan of "Smarter Choice". Just it was the smarter choice for themselves this time round -:)
Thursday, November 09, 2006
The Doctor is making money off Intel
The good Doctor of Pervasive 64 bit Disinformation has started running Google ads. I have nothing against this. All power to him if he can make money writing what he writes best. However, what I cannot understand is that he has ads promoting Intel products on his page. Surely his ethics would prevent him promoting Intel's products since he believes they all deserve to be consigned to a landfill. I left him a post yesterday asking what was going on but he did not post my comment. Here's the screen grab:

See it for yourself:
http://sharikou.blogspot.com
-------------------------------------------------------
UPDATE
I tried clicking the ad links at the bottom of the page...
Link to article
...and for 3 out of 4 the first link on the subsequent Google ad page took me to Intel's web site. That's just hilarious man! I really hope the Doctor is getting a good laugh too...hopefully to the bank with all the money I hope he's making from Intel via Google.
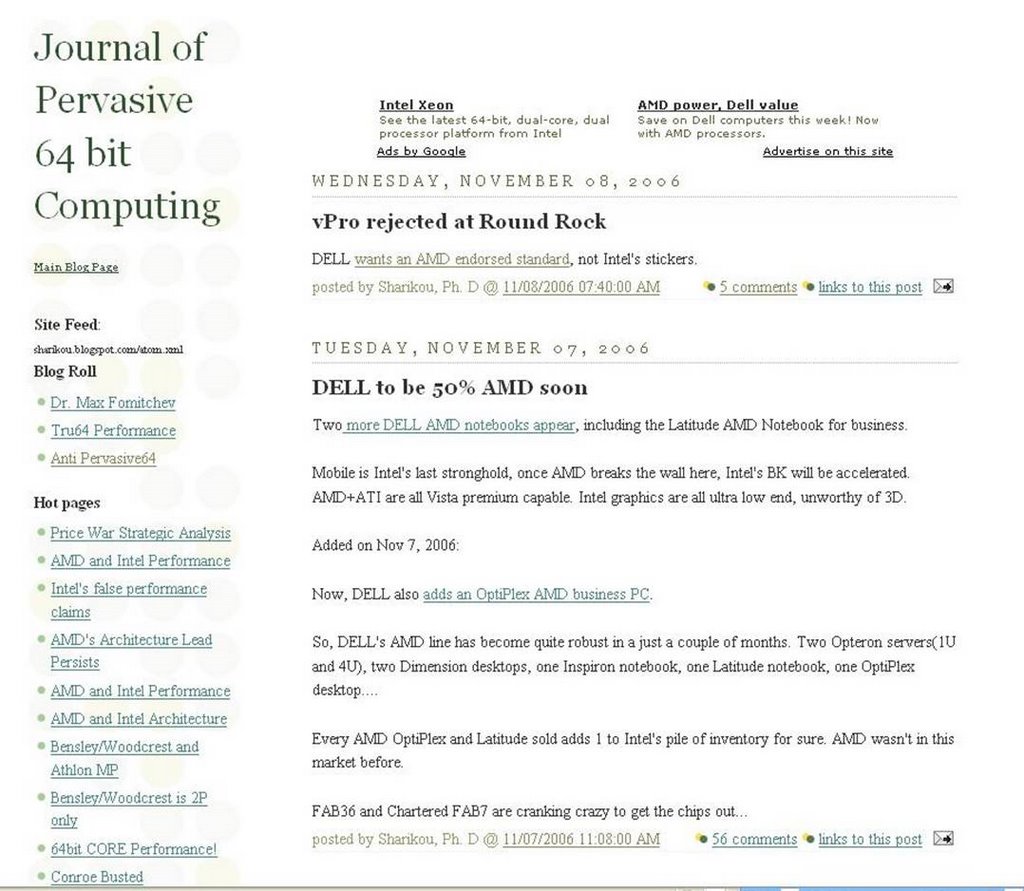
See it for yourself:
http://sharikou.blogspot.com
-------------------------------------------------------
UPDATE
I tried clicking the ad links at the bottom of the page...
Link to article
...and for 3 out of 4 the first link on the subsequent Google ad page took me to Intel's web site. That's just hilarious man! I really hope the Doctor is getting a good laugh too...hopefully to the bank with all the money I hope he's making from Intel via Google.
Dell deploys Quad Core
Dell with Quad Core Xeons on day 1. That's some time to market and endorsement:
http://biz.yahoo.com/bw/061108/20061108005201.html?.v=1
This is where the rubber hits the road and all the talk about K8L disappears into thin air as the product still does not exist. At this point all the dudes who are fantasizing about how AMD's quad core will kick Intel's ass get a dose of reality. It doesn't matter if your architecture is superior. If the product isn't in the market you ain't selling it. By Q2 Intel will have introduced more flavours of quad core desktop parts and dropped prices significantly below 999$ which is the launch price. In Q2 (hopefully) or perhaps Q3 AMD will introduce their quad core part but will not be able to price it in the same range as Intel will have almost a 3 qtr advantage to stabilize yields and reduce manufacture costs on the part. AMD will then have to play catch up again as Intel begins 45nm late 2007 followed by new mArch in 2008.
On a seperate but related note, Apple introduces the new Macbook with Core 2 Duo.
http://www.apple.com/macbook/macbook.html
Welcome to the party. It's about to get interesting!
-----------------------------------------------------
UPDATE
The opening line was meant to be "Dell with Quad Core Xeons on MINUS day 1. That's some time to market and endorsement:"
The implication here is the official Clovertown launch is actually 14th Nov. Dell has jumped the gun and also jumped every other OEM. There's a message in here and it's a Dell message...not Intel or AMD. Dell needs to win in servers to drive their margins up. Specially since they are losing share to HP.
http://biz.yahoo.com/bw/061108/20061108005201.html?.v=1
This is where the rubber hits the road and all the talk about K8L disappears into thin air as the product still does not exist. At this point all the dudes who are fantasizing about how AMD's quad core will kick Intel's ass get a dose of reality. It doesn't matter if your architecture is superior. If the product isn't in the market you ain't selling it. By Q2 Intel will have introduced more flavours of quad core desktop parts and dropped prices significantly below 999$ which is the launch price. In Q2 (hopefully) or perhaps Q3 AMD will introduce their quad core part but will not be able to price it in the same range as Intel will have almost a 3 qtr advantage to stabilize yields and reduce manufacture costs on the part. AMD will then have to play catch up again as Intel begins 45nm late 2007 followed by new mArch in 2008.
On a seperate but related note, Apple introduces the new Macbook with Core 2 Duo.
http://www.apple.com/macbook/macbook.html
Welcome to the party. It's about to get interesting!
-----------------------------------------------------
UPDATE
The opening line was meant to be "Dell with Quad Core Xeons on MINUS day 1. That's some time to market and endorsement:"
The implication here is the official Clovertown launch is actually 14th Nov. Dell has jumped the gun and also jumped every other OEM. There's a message in here and it's a Dell message...not Intel or AMD. Dell needs to win in servers to drive their margins up. Specially since they are losing share to HP.
Wednesday, November 08, 2006
Whose CPU margins are better
A very quick note. There is some wild gesticulation from the AMD "fannies" that AMD's CPU margins and cost structures are better than Intel's based on some ridiculous calculations (which I have already pointed out are baseless) from my good friend the Doctor. Here's why this is inaccurate and just a bunch of hand-waving from the AMD fans:
1. In Q3, Intel and AMD's gross margins were almost identical. However, AMD's margins are only for the high margin business of CPUs while Intel's are for CPUs + other businesses with significantly lower margins like flash, chipsets, mobos, etc. Furthermore, businesses like flash are actually a drag on profits recording a 116 million $ loss in Q3. On a CPU revenue of 5.8 billion out of a total 8.7 billion Intel's CPU margins would be significantly higher than the ~50% it recorded.
2. If AMD's margins are so good, why is it that it's net income for Q3 is only 1/10th of Intel's in spite of the fact that it's CPU revenues and market share are roughly 1/4th Intel's. And this is after Intel's net income being reduced by ~740 million due to Flash and Other losses.
The answer to both these is simple. Not only is Intel's cost structure better, it's ASPs are higher in the CPU business.
1. In Q3, Intel and AMD's gross margins were almost identical. However, AMD's margins are only for the high margin business of CPUs while Intel's are for CPUs + other businesses with significantly lower margins like flash, chipsets, mobos, etc. Furthermore, businesses like flash are actually a drag on profits recording a 116 million $ loss in Q3. On a CPU revenue of 5.8 billion out of a total 8.7 billion Intel's CPU margins would be significantly higher than the ~50% it recorded.
2. If AMD's margins are so good, why is it that it's net income for Q3 is only 1/10th of Intel's in spite of the fact that it's CPU revenues and market share are roughly 1/4th Intel's. And this is after Intel's net income being reduced by ~740 million due to Flash and Other losses.
The answer to both these is simple. Not only is Intel's cost structure better, it's ASPs are higher in the CPU business.
Sunday, November 05, 2006
Channel unhappy with AMD
First - I have been pretty busy last couple of weeks to post regularly to the blog. Instead, I've been trying to ensure comments get through and I can respond. Hopefully things will ease out this week and I'll be able to finish my Q3 take which has been in draft for some time. This post isn't a deep analysis. It's more to confirm the DIY channel frustration with AMD for shorting them on supply is starting to become visible with more re-sellers becoming vocal:
http://www.crn.com.au/story.aspx?CIID=67571&src=site-marq
http://www.theinquirer.net/default.aspx?article=35457
The impact of this to AMD is if this festers for another 2 quarters then it will take them a long time to win back channel trust/confidence even if supply does normalize. Those who work in the industry will understand this. Those who don't will issue blistering comments that they day AMD's supply problem is resolved, the channel will come running back to them. But that's not the way it happens. For the small guy round the corner, he feels screwed when either AMD or Intel give deeper discounts or supply preference to the big OEMs. It makes it incredibly hard for them to compete and watching a sale walk away because you didn't have the product is like seeing food on the table disappear. Intel has taken 2 years to recover from the chipset shortage. If this precipitates for AMD, they will lose a significant amount of channel momentum which will hurt them late next year once 65nm is ramped.
http://www.crn.com.au/story.aspx?CIID=67571&src=site-marq
http://www.theinquirer.net/default.aspx?article=35457
The impact of this to AMD is if this festers for another 2 quarters then it will take them a long time to win back channel trust/confidence even if supply does normalize. Those who work in the industry will understand this. Those who don't will issue blistering comments that they day AMD's supply problem is resolved, the channel will come running back to them. But that's not the way it happens. For the small guy round the corner, he feels screwed when either AMD or Intel give deeper discounts or supply preference to the big OEMs. It makes it incredibly hard for them to compete and watching a sale walk away because you didn't have the product is like seeing food on the table disappear. Intel has taken 2 years to recover from the chipset shortage. If this precipitates for AMD, they will lose a significant amount of channel momentum which will hurt them late next year once 65nm is ramped.
Thursday, October 26, 2006
Dell launches sub 500$ AMD notebooks
I want to start by saying this is NOT GOOD FOR AMD.
http://www.digitimes.com/systems/a20061024PR211.html (this link now needs a log in)
http://dailytech.com/article.aspx?newsid=4706
If you look at my posts/comments over the last few days I have been saying Dell is dragging AMD down the price stack and squeezing them on pricing thus hurting margins. I am now convinced this is what is happening. I know I said yesterday that AMD needs to do some discounting on notebooks to gain entry into new customers to break Intel's stronghold in the notebook segment but this sounds like they are going to start hurting themselves.
I repeat, if AMD was not running tight on capacity then it's ok to do these kinds of deals to keep the factories loaded. But considering the reports that they are starving teh channel on desktop parts for the last few months and now the TW ODMs are saying AMD may be short of mobile parts, surely they could have made some of these a higher bin and sold them for better margins at some of the other customers they are gaining entry into. Dell has no strategy and is heading into a death spiral of becoming commoditized but it's tragic they are dragging AMD down. As much as I think Intel is going to gain the momentum for the next 6-9 months, I think AMD is now throwing away the strategic leverage they have built so successfully in the market place with a good range of customers through these deals with Dell.
UPDATE
Dell's new AMD based notebooks are not sub 500$. In fact, a quick spec comparision shows they may actually be more expensive than an equivalent Centrino Duo. We probably need to wait 1-2 quarters to really see how this plays out.
http://www.digitimes.com/systems/a20061024PR211.html (this link now needs a log in)
http://dailytech.com/article.aspx?newsid=4706
If you look at my posts/comments over the last few days I have been saying Dell is dragging AMD down the price stack and squeezing them on pricing thus hurting margins. I am now convinced this is what is happening. I know I said yesterday that AMD needs to do some discounting on notebooks to gain entry into new customers to break Intel's stronghold in the notebook segment but this sounds like they are going to start hurting themselves.
I repeat, if AMD was not running tight on capacity then it's ok to do these kinds of deals to keep the factories loaded. But considering the reports that they are starving teh channel on desktop parts for the last few months and now the TW ODMs are saying AMD may be short of mobile parts, surely they could have made some of these a higher bin and sold them for better margins at some of the other customers they are gaining entry into. Dell has no strategy and is heading into a death spiral of becoming commoditized but it's tragic they are dragging AMD down. As much as I think Intel is going to gain the momentum for the next 6-9 months, I think AMD is now throwing away the strategic leverage they have built so successfully in the market place with a good range of customers through these deals with Dell.
UPDATE
Dell's new AMD based notebooks are not sub 500$. In fact, a quick spec comparision shows they may actually be more expensive than an equivalent Centrino Duo. We probably need to wait 1-2 quarters to really see how this plays out.
Wednesday, October 25, 2006
This is kind of funny
AMD which has just acquired ATI is promoting Crossfire systems with 3 out of 4 being Core 2 systems as best in class for gaming. I screen grabbed them before they get removed...


What makes this really funny is this is not on the ATI site but on the AMD site:
http://ati.amd.com/technology/crossfire/promotions.html
I wonder how quickly this comes down? Someone is getting a flamer in their e-mail when they get into work tomorrow!

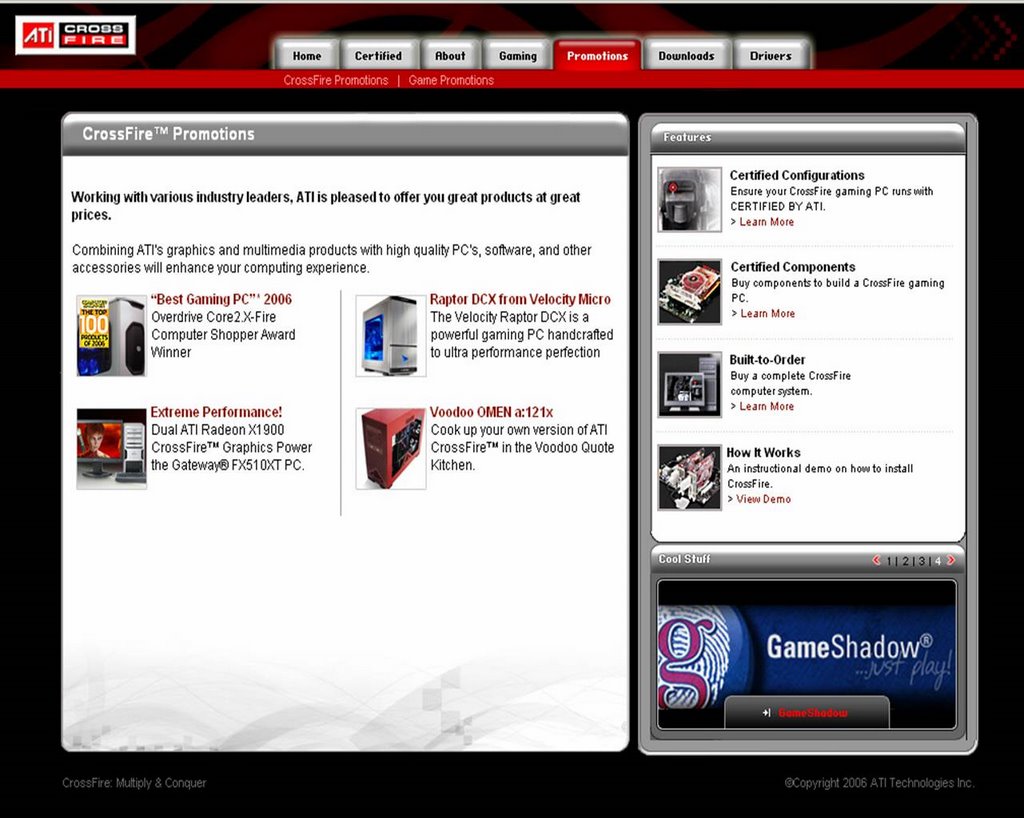


What makes this really funny is this is not on the ATI site but on the AMD site:
http://ati.amd.com/technology/crossfire/promotions.html
I wonder how quickly this comes down? Someone is getting a flamer in their e-mail when they get into work tomorrow!
AMD Earnings - a quick note
I want to move past the earnings announcements quickly cos they're stale news and I've taken too long to get to this. Hence, just a quick note on AMD:
1. Overall, their quarter came in on track more or less as I'd predicted including the fact they'd have a better quarter of it than Intel financially. The market share discussion also sees some light with the following assessment from Mercury Research - that both gained share from Via but Intel gained 3 points of share while AMD gained 1 point. The key here is AMD's leaps in market share are abating.
Q3 06 Market Share
2. The inventory issue (up by 15%) is worrying and my assessment is that this build up is really a result of Dell not being able to sell everything that was built for them...or just having the wrong SKUs.
3. Margins took a substantial beating down ~5.5%. A few things happened here. First, AMD's growth in servers slowed down relative to the pace they've been managing past few quarters due to Woodcrest. Those margins were allowing them to sell client parts (desktop specifically) at a large discount to gain share. Second, Intel competitive pricing really hit them and they had to take big price drops in the desktop segment which is where they have strength after server. Third, they are chasing low margin deals like Dell to secure entry into new customers like Dell and the PRC OEMs.
4. Unit volume growth was high but overall market share gain was just 1%. Intel took 3% - all of it from Via. I'd also predicted that they would do everything to keep their factories full and it looks like they did.
5. They are clearly short-changing the channel on supply and price competitiveness and this is a chink in their armour that will hurt them over the next few quarters.
Looking forward, AMD didn't provide much in the way of guidance. My thoughts:
- It is crucial for them to win back Opeteron share where they are losing to Woodcrest. I suspect they think Dell will help them do that but you cannot have Woodcrest grow to 40% of the DP market by unit and assume it's all the low end of the market from a system pricing POV.
- They should hold desktop pricing even if it means losing share and hope pricing stabilizes as Intel & AMD have said it might.
- Mobile - they should be willing to drop price in this segment to gain entry into new customers before Intel launches Santa Rosa. Frankly, even though AMD claims a 50% sequantial growth in mobile QoQ, considering the small base they have this is probably not as impressive as it sounds when you think the mobile market is growing at 20-30%. If they hope to dent Intel's stranglehold on this high margin segment they must be willing to make some trade offs.
Overall, looking into Q4 I think AMD still has it's job cut out. They will reap the benefits on cost and hence margins moving to 65nm but will be negated by their need to sustain market share. I would not be surprised if Intel extended it's Oct 22 price drop beyond low end desktop SKUs if required to keep AMD on the defensive. They need to gain market share because adjusting inventory to customer needs is easier said than done so that optimization they talk about may or may not happen. The incremental 60 million worth inventory accumulated this qtr if they've built the wrong product is going to either have to be sold or written off. Either way, it's going to hurt. Operating cash is important because they now have an ATI acquisition to pay debt on. AMD has a dilemma pulling them in two opposite directions. I suspect in Q4 they will actually cede share to hold pricing and margins. While everyone is focussed on AMD starting 65nm shipments, Intel too is increasing their 65nm and reducing 90nm every day so the battle for cost efficiency is tough...specially since the Core products have smaller die sizes.
With nothing left of Via, next quarter will truly tell who is gaining share and who is losing it. I still predict AMD will lose share and Intel will gain it. Remember, 3% of the remaining market is more than 1% in absolute volume terms. Momentum is swinging back to Intel and Q4 will show us that.
1. Overall, their quarter came in on track more or less as I'd predicted including the fact they'd have a better quarter of it than Intel financially. The market share discussion also sees some light with the following assessment from Mercury Research - that both gained share from Via but Intel gained 3 points of share while AMD gained 1 point. The key here is AMD's leaps in market share are abating.
Q3 06 Market Share
2. The inventory issue (up by 15%) is worrying and my assessment is that this build up is really a result of Dell not being able to sell everything that was built for them...or just having the wrong SKUs.
3. Margins took a substantial beating down ~5.5%. A few things happened here. First, AMD's growth in servers slowed down relative to the pace they've been managing past few quarters due to Woodcrest. Those margins were allowing them to sell client parts (desktop specifically) at a large discount to gain share. Second, Intel competitive pricing really hit them and they had to take big price drops in the desktop segment which is where they have strength after server. Third, they are chasing low margin deals like Dell to secure entry into new customers like Dell and the PRC OEMs.
4. Unit volume growth was high but overall market share gain was just 1%. Intel took 3% - all of it from Via. I'd also predicted that they would do everything to keep their factories full and it looks like they did.
5. They are clearly short-changing the channel on supply and price competitiveness and this is a chink in their armour that will hurt them over the next few quarters.
Looking forward, AMD didn't provide much in the way of guidance. My thoughts:
- It is crucial for them to win back Opeteron share where they are losing to Woodcrest. I suspect they think Dell will help them do that but you cannot have Woodcrest grow to 40% of the DP market by unit and assume it's all the low end of the market from a system pricing POV.
- They should hold desktop pricing even if it means losing share and hope pricing stabilizes as Intel & AMD have said it might.
- Mobile - they should be willing to drop price in this segment to gain entry into new customers before Intel launches Santa Rosa. Frankly, even though AMD claims a 50% sequantial growth in mobile QoQ, considering the small base they have this is probably not as impressive as it sounds when you think the mobile market is growing at 20-30%. If they hope to dent Intel's stranglehold on this high margin segment they must be willing to make some trade offs.
Overall, looking into Q4 I think AMD still has it's job cut out. They will reap the benefits on cost and hence margins moving to 65nm but will be negated by their need to sustain market share. I would not be surprised if Intel extended it's Oct 22 price drop beyond low end desktop SKUs if required to keep AMD on the defensive. They need to gain market share because adjusting inventory to customer needs is easier said than done so that optimization they talk about may or may not happen. The incremental 60 million worth inventory accumulated this qtr if they've built the wrong product is going to either have to be sold or written off. Either way, it's going to hurt. Operating cash is important because they now have an ATI acquisition to pay debt on. AMD has a dilemma pulling them in two opposite directions. I suspect in Q4 they will actually cede share to hold pricing and margins. While everyone is focussed on AMD starting 65nm shipments, Intel too is increasing their 65nm and reducing 90nm every day so the battle for cost efficiency is tough...specially since the Core products have smaller die sizes.
With nothing left of Via, next quarter will truly tell who is gaining share and who is losing it. I still predict AMD will lose share and Intel will gain it. Remember, 3% of the remaining market is more than 1% in absolute volume terms. Momentum is swinging back to Intel and Q4 will show us that.
Subscribe to:
Posts (Atom)